This article replaces a 2010 PersonalThailand opinion about loans between friends. A person’s nationality is not evidence of how responsibly they manage money.
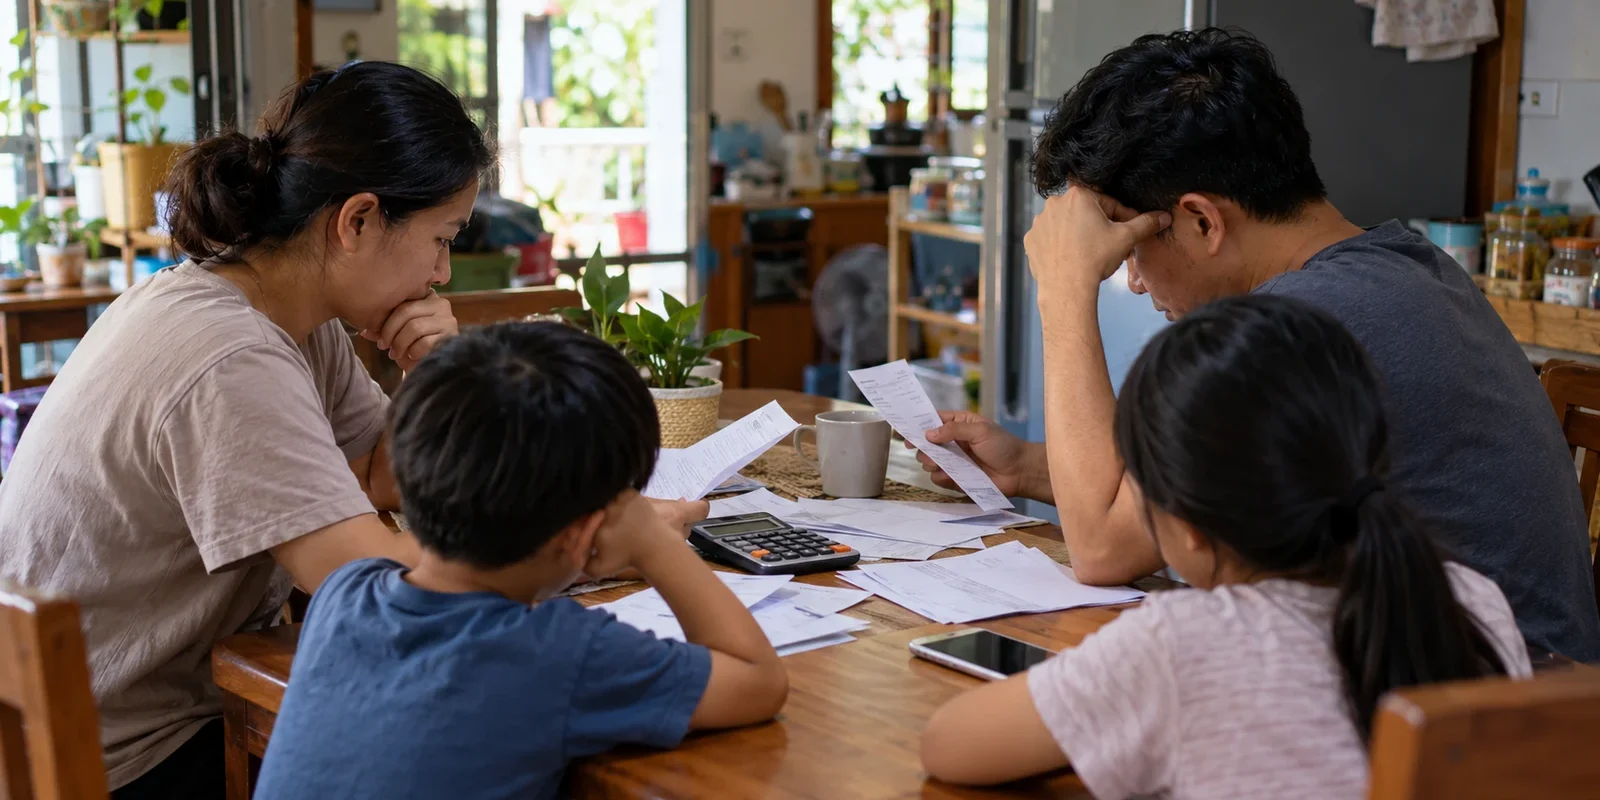
Debt is a common household challenge, not a character flaw unique to any culture. A family may borrow to cover education, housing, medical bills, farming expenses or a temporary loss of income. Others use credit for purchases they later struggle to afford. In Thailand, as in many countries, the safest response is to understand the loan terms, communicate early and seek appropriate help before arrears grow.
Why household debt is a policy issue in Thailand
The Bank of Thailand identifies household indebtedness as a structural issue with consequences for both household welfare and the wider economy. Its analysis does not reduce the problem to one national personality trait. It considers borrowing costs, earnings, formal and informal lending, and how borrowers are treated by financial institutions.
That broader perspective matters because not all borrowers have the same financial choices. A salaried employee with a documented credit history may access different products from a seasonal worker with irregular income. A debt that was affordable before an illness or job interruption may suddenly become difficult to service. People also differ in their legal eligibility for particular financial assistance programmes.
Understand what kind of loan you are considering
A regulated personal loan, a credit card balance, a mortgage and an informal loan from a neighbour involve different contracts and risks. Before borrowing, ask how interest is calculated, when instalments fall due, whether a missed payment produces charges and what the total cost will be if the full schedule is followed.
Informal credit can sometimes appear convenient because decisions are quick and documentation is minimal. That convenience can conceal serious problems if the lender provides no clear written terms, changes payment demands or uses intimidation. Borrowers should avoid agreeing to terms they cannot read or understand and seek professional guidance when a lender’s conduct appears threatening.
It is equally important to distinguish receiving financial help as a gift from receiving a loan. People who lend money to family or friends should discuss expectations openly rather than relying on assumptions that can damage relationships later.
If you lend money to someone you know
The original 2010 post assumed a loan to a Thai person was effectively always a gift. This sweeping assertion was unsupported and unfair. A better approach is to decide the purpose and boundaries of the arrangement before any money changes hands. If it is a gift, say so. If repayment is expected, specify the amount, timetable and an appropriate record in a format both people understand.
Neither party benefits from humiliation or stereotypes when payments become late. A lender should not threaten, publicly shame or harass a borrower. A borrower who foresees a shortfall should explain the situation before a missed deadline rather than disappearing. For substantial sums, cross-border arrangements or disputed contracts, ask a qualified local adviser about applicable law and documentation.
What responsible lending means
The Bank of Thailand’s responsible-lending guidance describes obligations for regulated lenders to give clear information and offer appropriate restructuring opportunities to eligible customers experiencing difficulties. The policy does not mean that every borrower is entitled to write off a debt or receive a particular interest rate.
Eligibility varies by lender, loan type and customer circumstances. If you are already behind on payments, contact the lender using official channels, explain what you can realistically pay and ask for all proposed repayment terms in writing. Check how a restructuring would affect interest, repayment length, credit information and any security attached to the loan.
A payment holiday may reduce pressure temporarily but could also alter the final cost. Compare the total financial obligation, not just the next month’s instalment.
Build a household repayment plan
- List every debt. Record the lender, amount owed, interest basis and due date.
- Protect essential costs. Budget for housing, food, transport and necessary healthcare first.
- Track cash flow. Separate fixed income from seasonal or uncertain earnings.
- Avoid new expensive borrowing simply to keep an older loan appearing current without a realistic plan.
- Ask early for help. A conversation before default usually offers more choices than silence.
- Keep documents. Save agreements, receipts and copies of official correspondence.
For a borrower dealing with several creditors, prioritising only the loudest caller can be counterproductive. A written overview can help identify which bills carry the most serious consequences and which creditors might offer a sustainable adjustment.
Where to look for trustworthy support
Use the Bank of Thailand’s official financial consumer resources and your lender’s verified support channels. The bank’s household-debt measures announcement explains the principles behind formal restructuring and responsible credit. Because programmes and qualification rules can change, check the specific provider rather than trusting a social media promise of guaranteed debt cancellation.
Never send identification numbers, online banking credentials or an advance ‘release fee’ to someone who claims to be a debt adviser without verifying their identity. Assistance should improve financial clarity, not expose you to another fraud.
The best lesson from the 2010 debate is not about judging Thai borrowers. It is about fair expectations, transparent contracts and practical options when circumstances change. Those principles work in Thailand and anywhere else.