Moving back to your home country after years in Thailand can create two financial transitions at once: closing or restructuring your life in Thailand, and rebuilding a budget in a country where housing, healthcare, taxes and everyday costs may work differently. The 2006 version of this article recommended a payday-loan company as a convenient bridge. That is not responsible general advice. A better plan starts with cash flow, paperwork and the costs you can predict.
Updated: October 2026.
Build a realistic relocation budget
List one-time costs such as flights, excess luggage or shipping, rent deposits, temporary accommodation, insurance, school expenses and replacement household essentials. Add costs that will continue during the move: Thai rent until a tenancy ends, recurring subscriptions, debt repayments and any ongoing financial obligations in Thailand. Then estimate the first three months in the destination country, not just the cost of getting there.
Try to calculate a conservative cash reserve and distinguish accessible savings from money tied up in assets, deposits or currency accounts. If you expect a new job, leave room for a delayed first salary. Temporary lodging can become unexpectedly expensive when paperwork, housing searches or school registrations take longer than expected.
Understand how your tax residence may change
Leaving Thailand and arriving somewhere else does not automatically settle tax questions. The rules depend on days of residence, sources of income, tax treaties, past filings and the destination country’s law. Preserve wage statements, tax certificates, bank statements and records of investment or property disposals before closing local accounts.
For example, the UK government’s returning-resident tax guidance explains that people moving back to the UK may need to account for foreign income and gains and sometimes register for Self Assessment. This is UK-specific; someone returning to Sweden, Australia, the United States or another country needs its own tax authority’s guidance. Cross-border tax matters can justify advice from a qualified professional.
Sort out banking and access to money
Ask your banks how changing your address, phone number and residency status affects the account. Check whether you can receive identity-verification messages overseas, use your banking app with a replacement phone and access statements after leaving. An account that works perfectly while you are in Bangkok may become difficult to manage from abroad if you lose its registered mobile number.
Compare foreign-exchange costs for moving savings. Look beyond the displayed exchange rate to transfer fees and intermediary bank charges. It may help to transfer money in stages, but there is no universally best method. Do not carry or transfer funds using arrangements that misstate ownership or conceal required reporting.
Check your accommodation, deposits and contracts
Read rental notice periods, inspection clauses and deposit terms early. Document the property’s condition when leaving, request receipts and settle utility balances. If you own a vehicle or other valuable property, allow time for transfer formalities rather than assuming a quick cash sale is guaranteed. Keep digital copies of ownership papers and proof of payment.
Close or transfer subscriptions, phone plans, gym memberships and insurance policies only after confirming cancellation conditions. Some obligations may continue even after departure. Save confirmation emails in a secure folder that you can access from your destination country.
Healthcare, insurance and essential documents
Arrange continuity of any regular medication and check whether you will be covered by public or private healthcare upon arrival. Eligibility rules vary by country and personal circumstances; do not assume coverage begins automatically on the day of your flight. Consider medical records, children’s vaccination documents, driving documents and verified copies of civil-status records.
Make a practical inventory of what you need immediately after arrival: passport, visa or residency documents if relevant, birth certificates, bank access, a working phone and proof of your next address. Carry originals securely and maintain encrypted backups of documents you may need to replace.
Be cautious about payday loans and expensive credit
The old article promoted a specific short-term lender. High-cost credit can make a difficult move more expensive. The US Consumer Financial Protection Bureau warns that payday-loan charges can add up quickly and suggests considering less costly alternatives. Its discussion is US-focused, but the basic principle is useful: calculate the complete repayment cost before borrowing.
Explore whether spending can be delayed, a payment plan negotiated, or support obtained from a bank, employer, family member or appropriate community organisation. Borrowing to cover an uncertain relocation budget is especially risky if your new income is not yet secure.
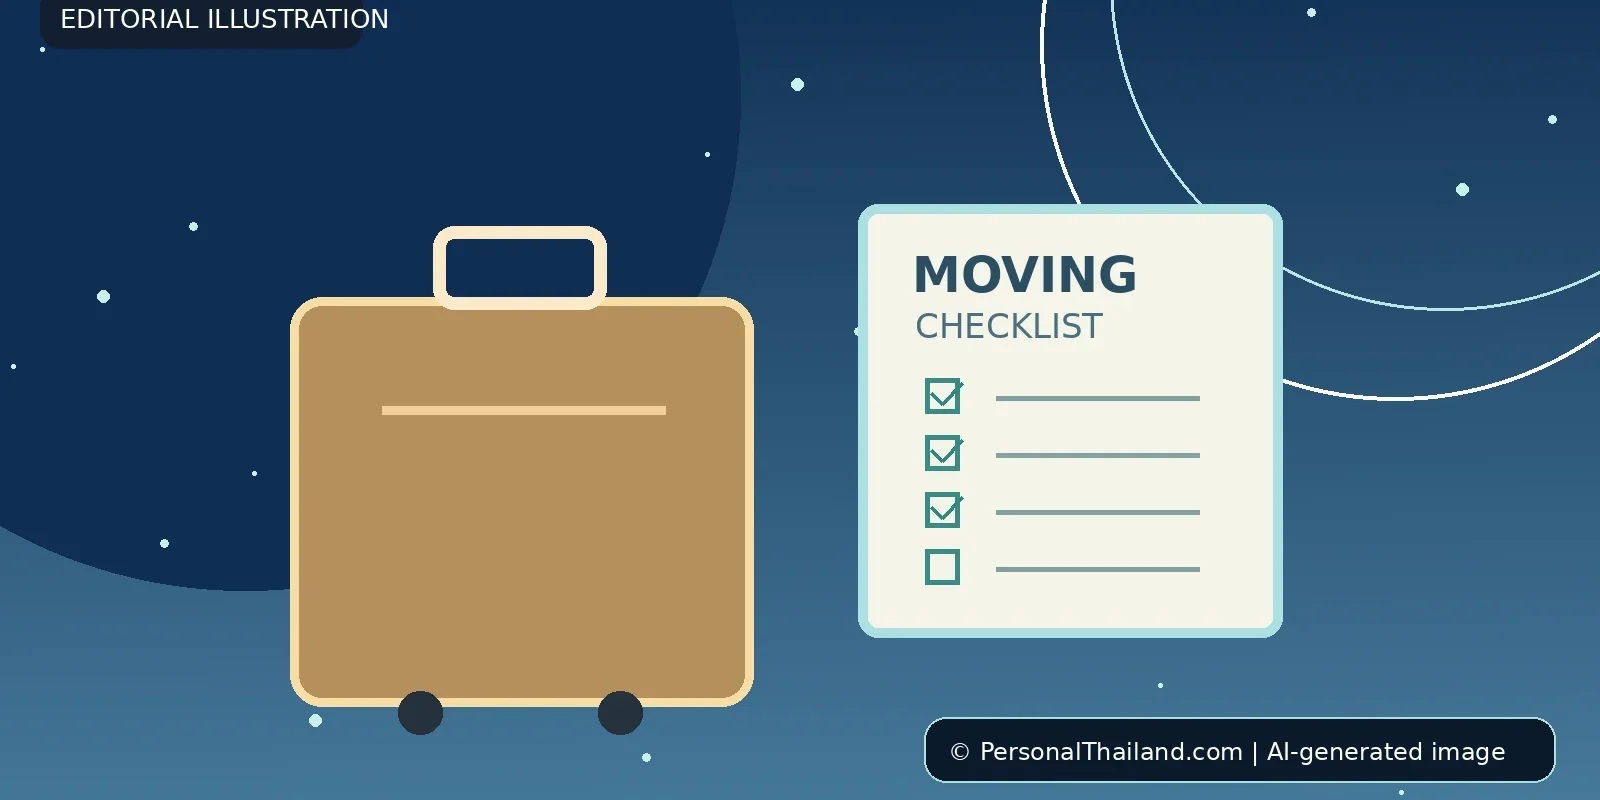
A six-week planning checklist
- Prepare a full moving budget with a cash contingency.
- Review residence, tax and reporting obligations in both countries.
- Confirm bank access, authentication and money-transfer costs.
- Give required notice on housing and service contracts.
- Arrange health coverage and gather essential documents.
- Keep proof of settled bills and completed account closures.
Returning home is often as much an administrative project as a travel plan. Paying attention to the details before leaving Thailand can reduce stress and help you start the next chapter without relying on expensive emergency credit.